

Last Updated on October 13, 2026 by Syed Sarim Naqvi
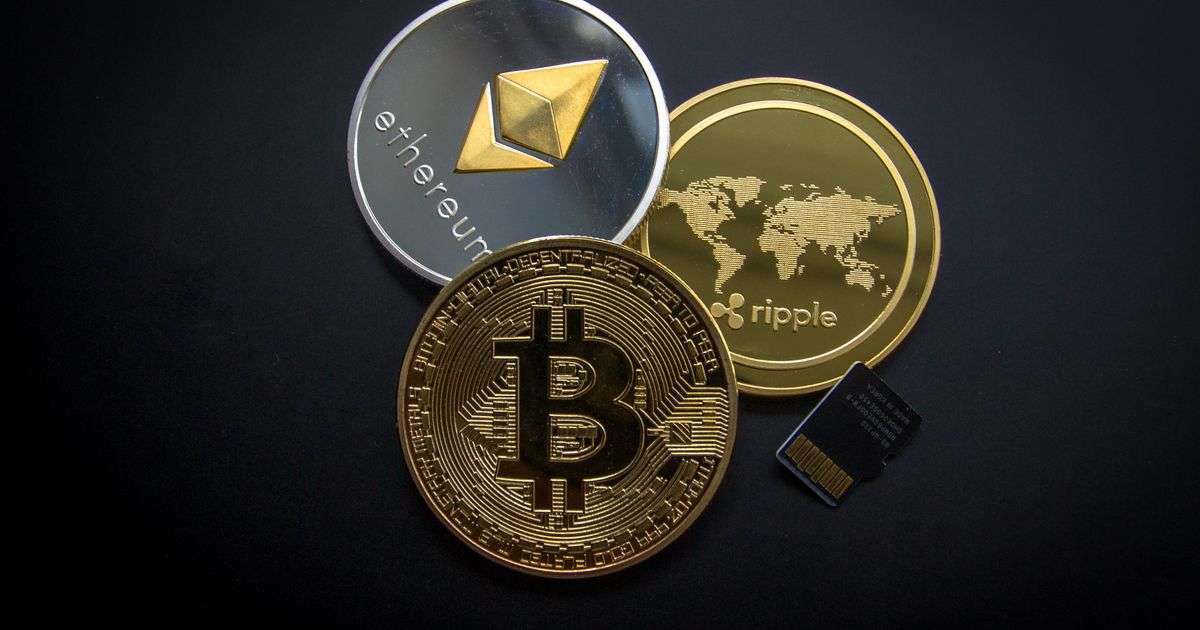
Crypto insurance is private cover that protects digital assets against theft, hacking, insider fraud or custodian failure, but it is not FDIC insurance, it mostly protects custodians and exchanges rather than individual users, and it never covers price drops or losing your own seed phrase. If you hold crypto, understanding what “insured” really means is more important than the headline coverage number.
Key Takeaways
- FDIC and SIPC do not cover cryptocurrency, even when held through an FDIC-insured bank
- Crypto cover is mainly bought by custodians and exchanges, and a user’s assets are covered only as a slice of that program
- Reported premiums run about 1% to 5% of covered value per year, with most institutional policies at 1% to 2.5% [VERIFY with a broker]
- Self-custody assets in a hardware wallet generally have no insurance
- Common exclusions include price drops, wrong-address transfers, lost seed phrases and rug pulls
This article is general information, not financial or insurance advice.
What Is Crypto Insurance?
Crypto insurance is specialized coverage that protects digital assets against theft, hacking, custodial failure and some smart contract exploits. Unlike traditional finance, where FDIC and SIPC back depositors, crypto holders bear the full loss unless a custodian or they themselves buy dedicated cover.
Does FDIC Insurance Cover Crypto?
No. FDIC deposit insurance covers dollar deposits at insured banks and does not extend to non-deposit products such as cryptocurrency, even if the account sits with an insured institution, according to Beinsure’s FDIC explainer. A custody guide from Spark notes that FDIC proposals in April 2026 for custody standards state that crypto assets will not receive deposit insurance.
| Where Your Crypto Sits | Insurance Situation |
|---|---|
| Bank deposit account | FDIC covers dollar deposits only, not crypto |
| Exchange account | Exchange cover usually protects its own hot-wallet systems, not individual balances |
| Institutional custodian | Covered as a slice of the custodian’s crime or specie policy, subject to limits and exclusions |
| Self-custody hardware wallet | No insurance exists |
What Types of Crypto Insurance Exist?
- Crime and fidelity cover: theft from hacking, insider dishonesty or other criminal acts, typically bought by the custodian or exchange
- Specie cover: protects digital assets in a custodian’s care, custody and control
- Errors and omissions and D&O: liability cover for the company and its leaders
- On-chain or parametric cover: pays on defined events such as a hack or depeg, with legal recognition that varies
A diligence report from Yirifi adds that standard cyber policies historically did not reimburse stolen crypto and often carry explicit digital asset exclusions, so “cyber insurance” and “crypto insurance” are not the same thing.
Who Actually Provides It?
Cobo’s 2026 guide lists Lloyd’s of London syndicates, Munich Re, Aon and Marsh among major participants, and describes Evertas as a Lloyd’s-linked firm with coverage up to $360 million. CryptoConsultz states that Lloyd’s syndicates have become the primary institutional capacity behind most crypto insurance sold today. Lloyd’s launched a Product Launchpad policy in 2021 to protect crypto held in online wallets against theft or hacking, according to Beinsure. This is the same specialist market we cover in 10 Strangest Insurance Policies Lloyd’s of London Has Written.
How Much Does It Cost?
Spark’s provider comparison reports premiums of roughly 1% to 5% of covered asset value annually, with most institutional policies between 1% and 2.5%, and says exchange hack cover rose about 35% year over year in early 2025. It also states that only 22% of exchanges maintain comprehensive hack coverage, a figure worth verifying independently before relying on it.
[YOUR EXPERIENCE/CASE STUDY HERE: if you work in crypto or have dealt with a custodian’s insurance disclosures, add your perspective.]What Is Not Covered?
- Price drops and market losses
- Sending crypto to the wrong address
- Losing your seed phrase or forgetting passwords
- Rug pulls and clicking suspicious links
- Government seizures
That list comes from USA Insure Today’s explainer, and it matches the general picture in institutional guides: insurance covers defined criminal or operational failures, not poor judgment or volatility.
Why Is “Insured” Such a Slippery Word?
A custodian saying “$500 million insured” can hide important details. Yirifi warns that “insured” tells you almost nothing about whether your assets are protected when lost, and recommends checking limits, whether the policy is per-incident or aggregate, and what is actually held in hot versus cold storage. For the largest exposures, protection often comes from legal structure, such as bankruptcy-remote segregation, rather than insurance.
How Does This Connect to Celebrity Insurance?
Crypto cover follows the same pattern as every unusual asset in this site: if value is concentrated and loss is possible, a specialist market prices it. Compare it with Fine Art Insurance Explained and Kidnap and Ransom Insurance Explained.
FAQ
Is my crypto insured if I leave it on an exchange?
Not necessarily. Exchange insurance typically protects the exchange’s own hot-wallet systems, not individual account balances, and terms vary by exchange.
Is crypto covered by FDIC?
No. FDIC insures deposits at insured banks and does not cover cryptocurrency, even if held through an insured institution.
Can I insure a hardware wallet?
Generally no. Guides on custody state that assets held personally in a hardware wallet have no insurance coverage.
What does crypto insurance cost?
Reported premiums run around 1% to 5% of covered value a year, with most institutional policies at 1% to 2.5%.
What does custody insurance cover?
Typically theft from hacking or insider fraud and certain loss scenarios in the custodian’s care, up to program limits and subject to exclusions.
Does cyber insurance cover stolen crypto?
Often not. Cyber policies historically paid for breach response costs rather than stolen crypto and may carry digital asset exclusions.
Glossary
- Specie Insurance: cover for valuable assets held in a custodian’s care and control.
- Crime Policy: cover for theft, fraud and employee dishonesty.
- Hot Wallet: an online wallet connected to the internet.
- Cold Storage: offline or air-gapped storage.
- Parametric Cover: pays when a defined on-chain event occurs.
Sources
- Spark: Crypto Insurance Providers, Coverage, Premiums and Claims (premium ranges, exchange coverage statistic)
- Spark: Crypto Custody Insurance Comparison (FDIC and SIPC position, April 2026 proposal)
- Cobo: Crypto Insurance, How to Protect Digital Assets (providers, coverage types)
- Beinsure: FDIC Deposit Insurance and Crypto (FDIC scope, Lloyd’s 2021 launch)
- DAG: Crypto Insurance and Custody (exchange gap, self-custody)
- CryptoConsultz: How to Insure Large Crypto Holdings (Lloyd’s capacity, custodian coverage structure)
- Yirifi: Crypto Insurance, What It Covers and the Gaps (cyber exclusions, “insured” caveat)
- USA Insure Today: What Is Crypto Insurance? (common exclusions)
Related reading: Content Creator and Influencer Insurance Explained · Space and Satellite Launch Insurance Explained
Published October 2026. The crypto insurance market changes quickly; verify current terms with providers and refresh this article regularly. Nothing here is financial advice.




Leave a Reply