Last Updated on September 16, 2026 by Syed Sarim Naqvi
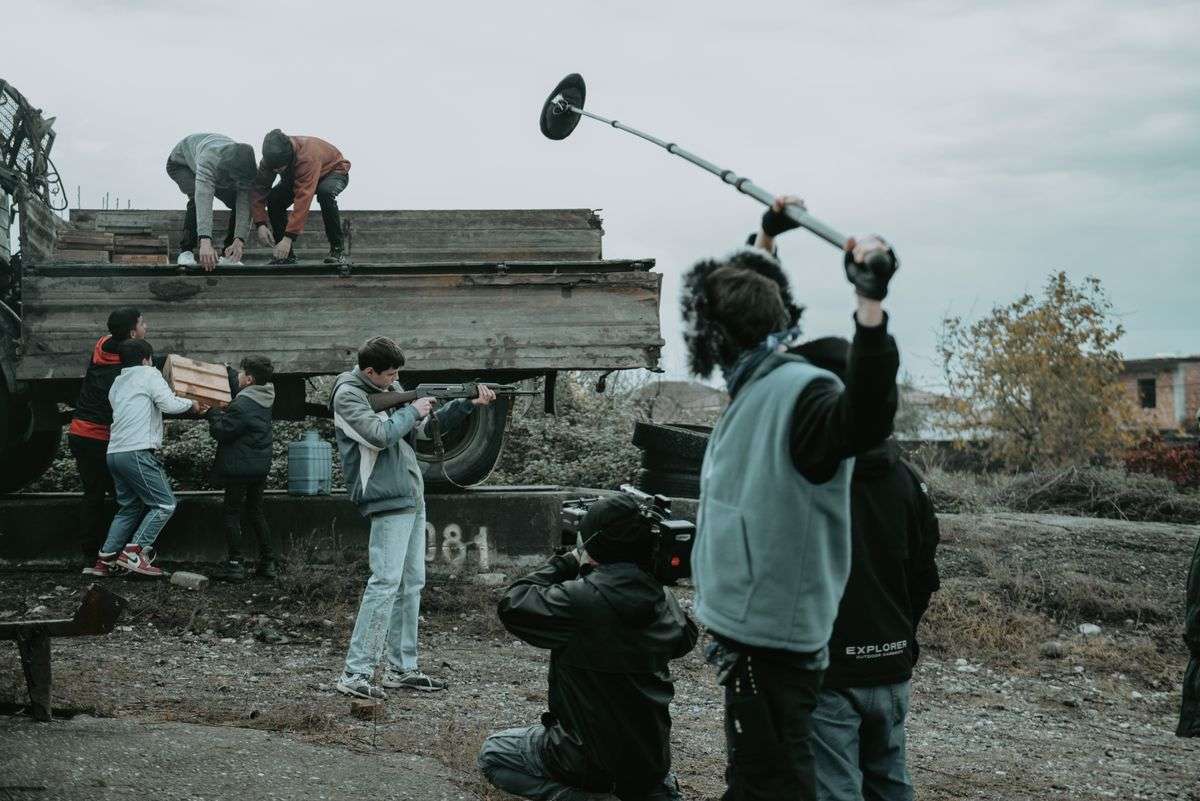
Stunt performer insurance is a specialized set of coverages — mainly workers’ compensation, production liability, and sometimes personal accident policies — that protect the people who perform Hollywood’s dangerous physical sequences, in a job some insiders describe as having close to a 100% injury rate over a career. Unlike the actors they double for, stunt performers are rarely covered by simple, blanket policies — coverage is fragmented, stunt-specific, and often excludes the most dangerous work entirely.
Key Takeaways
- Stunt work has been described by industry insiders as the only job with a near-100% injury rate over a career, according to reporting in MovieMaker Magazine (2024)
- Standard cast/crew insurance does not automatically cover stunt performers — coverage varies by country and production
- Insurers often exclude the most dangerous stunts outright, meaning the actor or studio effectively self-insures that risk
- Workers’ compensation, not personal accident insurance, is the primary safety net for on-set stunt injuries in the US
- Stunt coordinators with strong safety track records can influence what insurers will approve — and at what price
What Is Stunt Performer Insurance?
Stunt performer insurance isn’t one single product — it’s a layered combination of coverages that together protect the physical risk of professional stunt work. The three main layers are: production liability insurance (covering the film production itself), workers’ compensation (covering the employee-performer directly), and, in some cases, supplemental personal accident policies for individual performers.
Why Isn’t There Just One Simple Policy?
Because stunt work varies so wildly in risk — a controlled stage fall is a completely different underwriting problem than a motorcycle jump off a cliff — insurers price and structure coverage stunt-by-stunt rather than as a blanket policy. Production liability insurance can cover crew injury on set, but many stunts are considered too dangerous to be included in a standard policy at all, and insurers frequently write explicit exclusions for anything labeled a “hazardous” stunt performed without their prior sign-off.
How Dangerous Is Stunt Work, Really?
This is the detail that makes stunt insurance genuinely unusual among entertainment-industry coverages: according to industry commentary published in MovieMaker Magazine (2024), stunt performers are sometimes described as having the only job in the world with a 100% injury rate over the course of a career — encompassing everything from catastrophic accidents to concussions that performers have historically hidden for fear of losing work.
- Injury culture: Reporting from MovieMaker Magazine (2024) notes a long-standing culture of concealing concussions, driven by fear of appearing weak or losing future bookings
- Coverage gaps: The insurance that covers a film’s cast and crew does not necessarily extend to stunt performers by default
- Complexity: Coverage structures vary significantly between the US, Canada, and other filming locations
Who Actually Pays When a Stunt Performer Is Injured?
In the United States, workers’ compensation is generally the primary mechanism — it covers medical expenses and wage replacement for employees (including stunt performers, actors, and crew) injured while performing job duties on a production, and provides death benefits to dependents in the worst-case scenario. This is separate from, and more foundational than, any specific “stunt insurance” product.
Why Do Insurers Sometimes Refuse to Cover the Most Dangerous Stunts?
Even A-list productions run into this wall. Reporting from The Hustle (2024) on the Mission: Impossible franchise notes that insurance experts believe policies for the films may exclude the most extreme sequences — meaning that for stunts like a motorcycle cliff jump, the star and studio may effectively be carrying that specific risk themselves rather than transferring it to an insurer. One insurance expert quoted in the piece put it plainly: if every actor performed stunts at that level, insurers “probably would not be able to insure productions anymore.”
[YOUR EXPERIENCE/CASE STUDY HERE — if you have a specific example of a production you’re familiar with negotiating stunt coverage, insert it here for added authority.]How Does a Stunt Coordinator Affect Insurance Costs?
A stunt coordinator’s resume and track record matter directly to underwriting. According to industry reporting from MFE Insurance, a coordinator with extensive experience and a strong safety record can liaise directly with insurers to negotiate broader inclusion of a production’s stunt work — and in some cases avoid extra premium loading that would otherwise apply.
Comparison: The Three Layers of Stunt-Related Coverage
| Coverage Type | What It Covers | Who It Protects | Key Limitation |
|---|---|---|---|
| Production Liability Insurance | On-set injury, property damage, general production risk | The production/studio | Often excludes stunts labeled “hazardous” without prior insurer approval |
| Workers’ Compensation | Medical costs, wage replacement, death benefits | Employees, including stunt performers, actors, crew | Only applies to those classified as employees of the production |
| Personal Accident/Supplemental Insurance | Additional coverage beyond workers’ comp | Individual performers who purchase it | Not standard or guaranteed across the industry |
What Do Stunt Performers Actually Earn — and Does It Reflect the Risk?
According to Acting Magazine (2025), average annual income for stunt performers ranges from roughly $50,000 to $100,000, with top stunt doubles on major films or TV shows earning $200,000 or more. Highly specialized performers who build long-term relationships with A-list actors — such as Heidi Moneymaker, known for doubling Scarlett Johansson in Marvel films — can command significantly more through union rates and production bonuses, though exact figures for top performers are rarely disclosed publicly. [VERIFY THIS STAT if citing exact current figures — union rate schedules change periodically.]
The Historical Evolution of Stunt Safety and Insurance
Stunt work professionalized gradually. From its emergence as a distinct skill in the early 1900s through the 1960s, stunts were typically performed by people who had already trained in a relevant discipline before entering the film industry. Today, performers must train across multiple disciplines — martial arts, stage combat, precision driving, and more — and must generally be certified members of a professional stunt performers’ organization to even obtain the insurance required to work on a professional set.
FAQ
Are stunt performers automatically covered by a film’s general production insurance?
Not necessarily. The insurance covering a film’s cast and crew does not automatically extend to stunt performers — coverage depends on the specific policy, the stunt’s classification, and the country where filming occurs.
Do insurers ever refuse to cover a specific stunt?
Yes. Insurers frequently exclude stunts they classify as “hazardous” unless they’ve explicitly approved them in advance, and in extreme cases (like some Mission: Impossible sequences), the most dangerous stunts may not be covered at all.
What’s the difference between workers’ compensation and stunt insurance?
Workers’ compensation is a broader, foundational coverage for any employee injured on the job, including stunt performers. “Stunt insurance” more specifically refers to production liability provisions and any supplemental coverage tied to specific high-risk sequences.
How much do stunt performers get paid, given the risk?
Reported average annual income is roughly $50,000–$100,000, with top performers on major productions earning $200,000 or more, according to industry reporting — though this varies significantly by experience, union status, and production budget.
Does a stunt coordinator’s experience actually affect insurance costs?
Yes — insurers weigh a coordinator’s safety track record when deciding how much of a production’s stunt work to include in coverage, and experienced coordinators can sometimes negotiate better terms.
Why do actors like Tom Cruise perform their own dangerous stunts?
Partly by choice and reputation-building, and partly because of the leverage that comes with being a producer on the project — but insurance experts note this shifts real financial risk onto the star and studio for sequences that may fall outside standard coverage.
Glossary
- Production Liability Insurance: Coverage protecting a film/TV production against on-set injury and property damage claims.
- Stunt Coordinator: The professional responsible for designing, rehearsing, and overseeing the safety of a production’s stunt sequences.
- Hazardous Stunt Exclusion: A common insurance policy clause excluding coverage for stunts an insurer deems especially dangerous, unless pre-approved.
- Second Unit: A film crew, often led by the stunt department, responsible for shooting action sequences separately from the main director’s unit.
Author Bio
[AUTHOR BIO PLACEHOLDER — insert name, relevant credentials (e.g., entertainment insurance background, film production experience, or journalism credentials), and a link to a professional profile such as LinkedIn.]Sources
- MovieMaker Magazine — Dirty Secrets of Stunt Work: A Job With a 100% Injury Rate — supports the injury-rate and concussion-culture claims
- The Hustle — How Hollywood Insures Its Biggest Stunts — supports the Mission: Impossible coverage-exclusion example
- MFE Insurance — Production Liability & Stunt-Related Claims — supports the hazardous-stunt exclusion and coordinator-influence claims
- AZ Hurt on the Job — Lights, Camera, Safety? Unmasking Workplace Hazards in Hollywood — supports the workers’ compensation explanation
- Acting Magazine — How Much Do Stunt Doubles Make? — supports the stunt performer income figures
- MovieInsure — The Vital Role of Stunt Insurance in Movie Productions — supports general stunt insurance framing
Internal Link Suggestions
- Link to Sports Stars Who Insured Their Bodies for Millions using anchor text “athletes who insure their bodies against injury” — natural bridge between stunt performers and athletes as physically at-risk professionals.
- Link to How Celebrity Body Parts Insurance Actually Works using anchor text “how body-part insurance underwriting works” — connects the underwriting logic.
- Link to Esports Insurance using anchor text “other high-risk professions with coverage gaps” — thematic link between under-covered physical professions.
- Suggested backlink: Add a link to this new stunt-insurance article FROM the “Sports Stars” article, in a section discussing behind-the-scenes entertainment-industry risk, using anchor text “how Hollywood insures its stunt performers.”
Published September 2026. Stunt insurance practices and injury statistics referenced here should be periodically reverified, as production insurance markets and safety standards evolve.

Leave a Reply